 Probity
Check the broker's SDE against the tax returns, before you price the LOI.
Is the broker's number real? SDE, seller's discretionary earnings, is the profit figure on the listing, and it is built to sell the business. Probity reads three years of the seller's tax returns and shows what the business actually earned. Free on two new deals a month, no card.
Free accounts open soon. Leave your email and you are in first. The free account never asks for a card.
| Figure | 2023 | 2024 |
|---|---|---|
| Broker's SDE, from the listing | $570,000 | $420,000 |
| SDE from the tax returns, one-time items out | $398,420 | $298,780 |
| Gap | $171,580 | $121,220 |
Why the broker's 2024 number is $121,220 above the returns:
- -$83,520 Adjustment for market rent.
- -$18,000 Section 179 equipment deduction. It never reduced the return's income, so adding it back counts it twice.
- -$12,000 Owner vehicle. The returns and the CIM can't show whether it's personal.
- -$7,700 Not itemized. The broker doesn't say what it is.
Every number in the sample links to the tax-return page it came from.
Why the tax returns
The SDE Recast rebuilds the seller's tax returns into what the business would actually pay you to run it. Three years, line by line, every number linked to the page it came from. One-time items come out and are listed on their own. Your own estimates for rent, manager pay and anything else you would change roll into a Buyer SDE. Then it walks line by line from your number to the broker's number, so you can see exactly what the gap is made of.
It runs on two new deals a month at no cost, with no card. Re-running a deal you already started never counts, and everything you have run stays on screen.
The returns are the floor, not the ceiling
A seller's incentive with the IRS runs the opposite direction from a seller's incentive with a buyer. The tax return understates income if it understates anything, which makes it the one document you can trust as a floor.
Your lender is going to spread the same returns
An SBA lender builds its own spread from the same three years of returns before it will fund a dollar. Doing it first means their number is never a surprise.
An add-back is a claim, and claims need testing
Every add-back on a broker's schedule is a story about a dollar that supposedly doesn't count. Some are real. The ones that aren't are purchase price you'd be donating. A documented add-back, tied to an actual number, gets accepted by buyers and lenders far more often than one that isn't: about 90% of the time, versus 60-70% for an undocumented one (BizBuySell).
Tax returns
3 years, every page
Spread
line by line, year over year
Buyer SDE
after your adjustments
Bridge to the broker's number
what closes the gap
Tax returns
3 years, every page
Spread
line by line, year over year
Buyer SDE
after your adjustments
Bridge to the broker's number
what closes the gap
What's in the free account
It replaces the spreadsheet most buyers start with, and it stays free. No card.
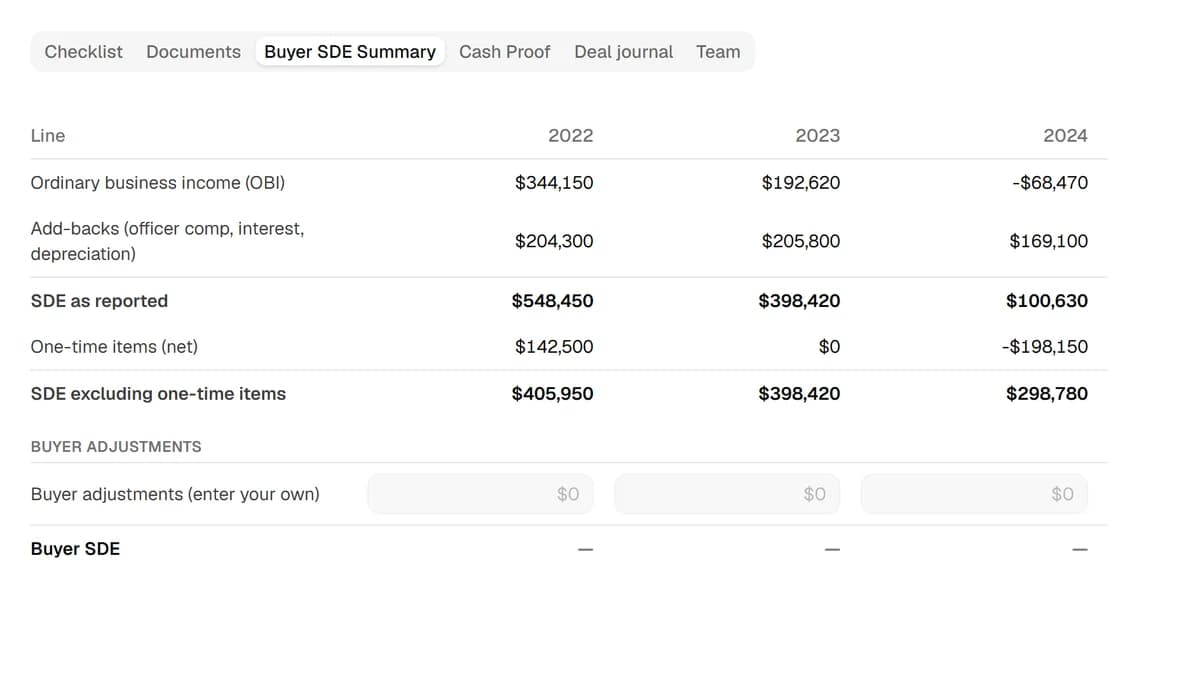
The SDE Recast, on two new deals a month
Three years of the seller's business tax returns, rebuilt line by line, every figure linked to its page. One-time items separated out. Your own estimates rolling into a Buyer SDE. The bridge to the broker's number. Free.
See it on the sample deal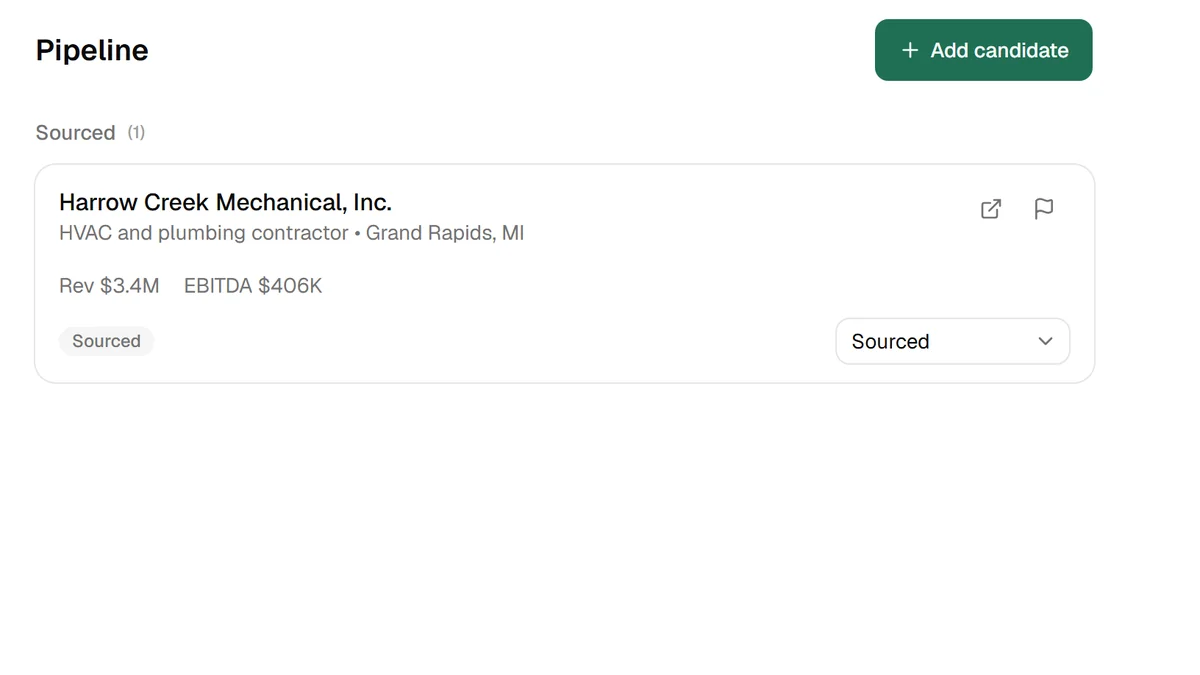
Clip listings, checked against your buy box
Save a listing from any broker site in one click. Write your buy box once, the criteria a business has to meet, and every listing you clip is checked against it. Each deal gets its own stage, notes, and a documents tab.
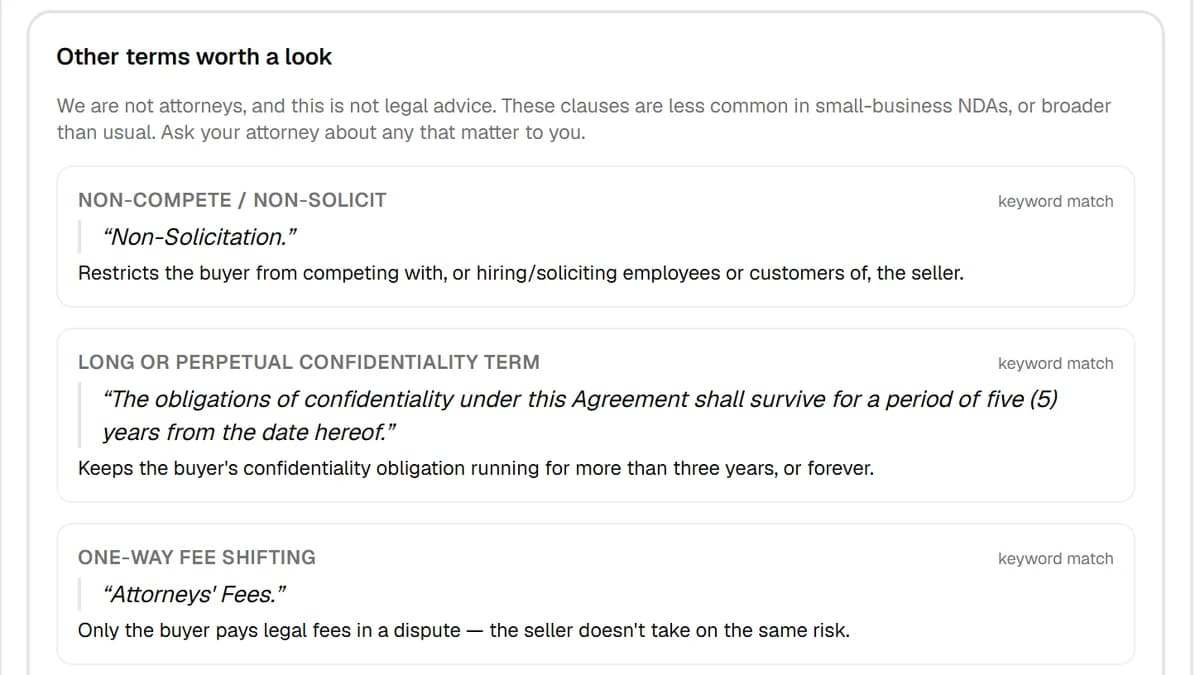
Check the NDA before you sign it
Upload or paste the broker's NDA. It quotes back the clauses worth a second look, such as a non-solicit, a five-year term, or who pays whose legal fees, with the section each one came from. It flags; it is not legal advice.
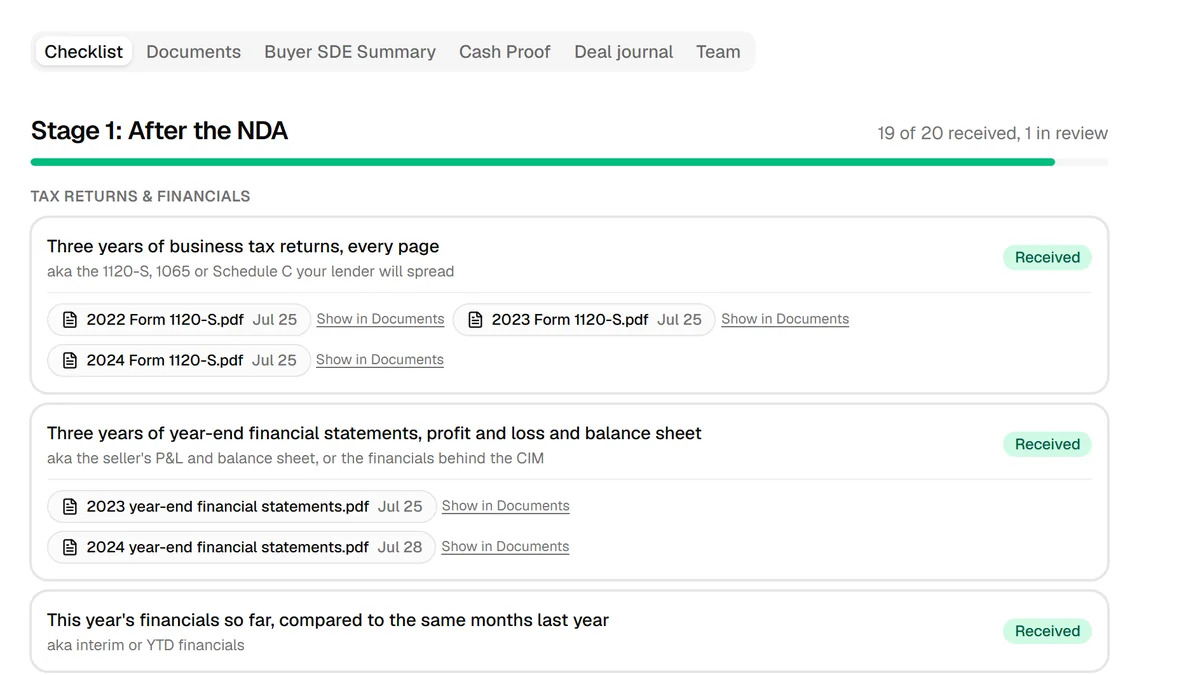
The four-stage diligence checklist
91 requests in four stages: after the NDA, right after the LOI, what the lender will ask for, and day one. Plus 12 public-record checks you can run yourself. Track what has arrived, or download it as a spreadsheet.
See every item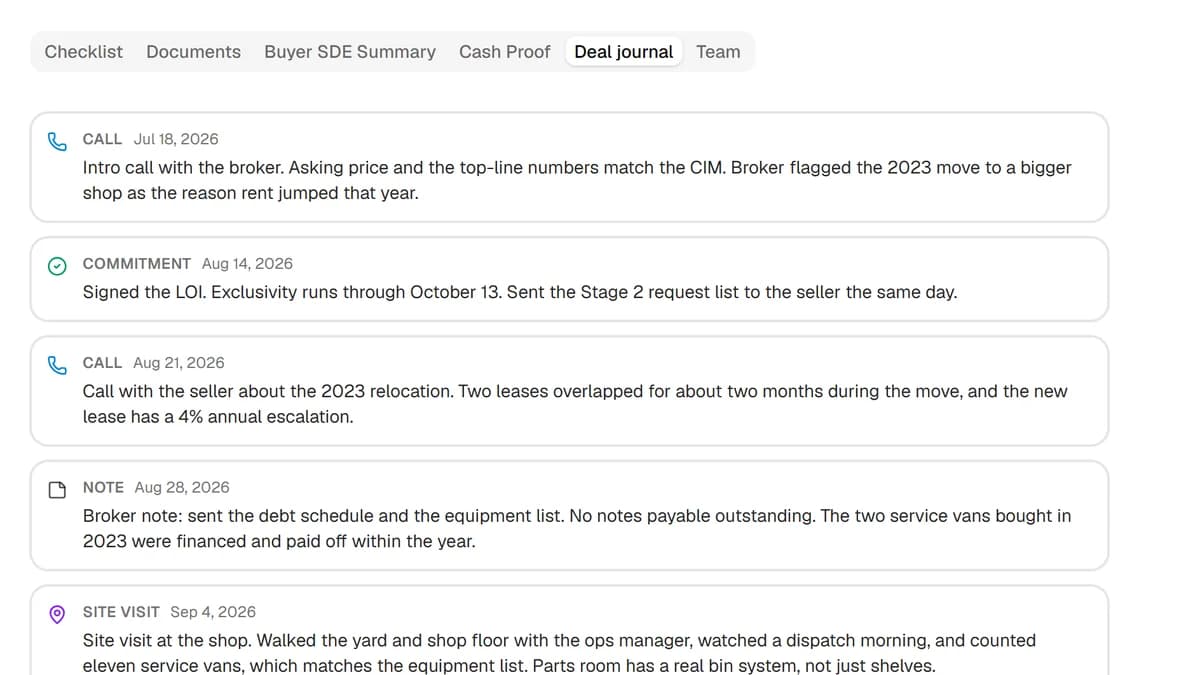
Deal journal, and site visits from your phone
Calls, notes and commitments in one place, tied to the deal. On a site visit, add photos, voice memos and notes from your phone, even with no signal. They sync when you are back online.
From search to a signed LOI
Write your buy box
the criteria a business has to meet: industry, size, cash flow, where, and what you won't touch
Clip listings into your pipeline
one click from any broker site, checked against your buy box
Or let your alerts screen themselves
forward your alert emails and every listing arrives already checked, instead of clipping them one at a time
Spread the returns
the SDE Recast, tax returns line by line
Price it and sign the LOI
price it with your Buyer SDE, then sign
Write your buy box
the criteria a business has to meet: industry, size, cash flow, where, and what you won't touch
Clip listings into your pipeline
one click from any broker site, checked against your buy box
Or let your alerts screen themselves
forward your alert emails and every listing arrives already checked, instead of clipping them one at a time
Spread the returns
the SDE Recast, tax returns line by line
Price it and sign the LOI
price it with your Buyer SDE, then sign
At the LOI, Cash Proof takes over that one deal: the seller's bank statements tied to the tax returns, month by month. $995 once, and it moves with you if the deal dies.
Screen your alerts against your buy box
Forward your marketplace and broker alert emails to a private address. Every listing comes back checked against your buy box and marked Met, Flagged or Not met, with the reason it landed there. The results sit in a Screened inbox. You add the ones worth a look to your pipeline and dismiss the rest. There is no daily email to unsubscribe from.
A listing you clip yourself is checked against the same buy box for free. What Pro adds is not having to clip them: your alerts arrive already screened. $79.99 a month.
When the file has to leave your screen
The recast is free to look at. The month it has to go to a lender, a banker or your CPA, Pro turns it into an Excel workbook with live formulas or a PDF they can drop straight into the file.
$79.99 a month. Cancel when it has gone where it needed to go, and start it again the month you need it next. One subscription covers every deal in your pipeline, up to twenty new deals a month.
Excel with live formulas, or a lender-ready PDF, on any recast
Automatic screening of your forwarded alerts against your buy box
Questions answered from the deal's own documents, with the page each answer came from
Site-visit questions drafted from the deal, and your dictated debrief written up
One partner seat
Prove the cash before you close.
The tax returns tell you what the seller reported. The bank statements tell you what actually came in and went out. Cash Proof ties the two together month by month: deposits against reported revenue, withdrawals against reported costs, what does not match, and the statement page behind every figure.
$995 once, on one deal, bought when you reach the LOI. It opens the Excel and PDF downloads and the document questions on that deal with no Pro subscription, and it seats your CPA, your attorney and your lender on whatever you choose to share. If the deal dies it moves to the next one, as many times as you need for 12 months.
What it is not
Not a quality of earnings report. Not an audit. Not an opinion of value or on whether to buy. Nobody at Probity looks at your deal. It can show you a gap; it cannot explain one, because it does not read the general ledger. Run it before you decide whether a quality of earnings report is worth paying for.
New SBA rules for business buyers, effective October 1, 2026. Every SBA loan to buy a business is sized by a coverage test on the business's earnings, not the broker's number, whatever the price. On a first-time purchase or one company buying another, at a purchase price of $3 million or more, your lender also has to order a Quality of Earnings report on the seller's books, per SOP 50 10 8.1. Cash Proof does not satisfy that requirement; it is what you run first, to decide whether a Quality of Earnings report will find anything. Confirm with your lender.
What changes for buyers →Built by a CFO who has underwritten and closed acquisitions. He does not look at your deal and does not advise you on it.
Get early accessFree accounts open soon. Leave your email and you are in first. The free account never asks for a card.